Inflation Calculator – US CPI Purchasing Power Calculator
Find out what a dollar amount from any year is worth in any other year, from 1913 to 2025. Uses official BLS CPI-U data. Calculates total inflation, annual rate, and shows a full year by year breakdown.
Inflation Calculator
Compare purchasing power between any two years from 1913 to 2025 using official US CPI-U data.
Based on annual average CPI-U published by the US Bureau of Labor Statistics, base period 1982-84 = 100. CPI tracks a national basket of goods, so your personal inflation rate will differ depending on what you actually spend on.
How this inflation calculator uses real CPI data instead of a fixed inflation percentage
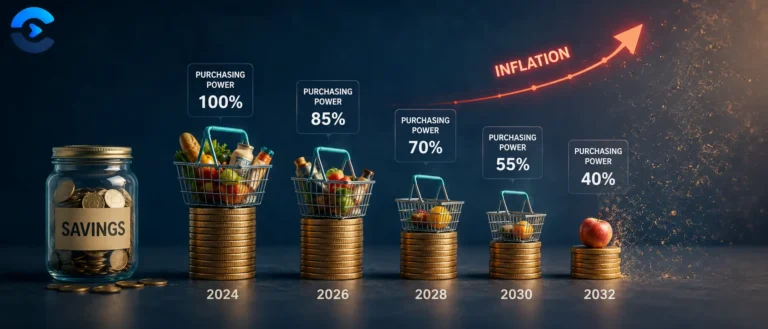
A lot of inflation calculators just apply a flat assumed rate, say 3 percent a year, compounded across however many years you ask for. This tool does not do that. It runs on a hardcoded table of actual U.S. Consumer Price Index for All Urban Consumers, CPI-U, annual averages published by the Bureau of Labor Statistics, covering every year from 1913 through 2025. Because it uses real historical index values rather than an assumed constant rate, it captures the actual bumpy path of inflation, including the high inflation years of the late 1970s and the near zero years around 2009 and 2015, not a smoothed average.
This is a static lookup table baked into the JavaScript file, not a live API call. There is no network request involved in the calculation itself, everything runs instantly from data already loaded in your browser.
What CPI-U actually measures
The index is set to a base of 100 for the average of 1982 through 1984. A CPI value of 319.8 for 2025 means, in broad terms, that the same basket of goods and services that cost $100 in the 1982 to 1984 base period costs about $319.80 in 2025. The ratio between any two years’ CPI values is the entire basis for the tool’s math.
Worked example using the tool’s actual embedded data: $100 in 1980, when CPI-U averaged 82.4, converted to 2025 dollars, where CPI-U averaged 319.8. The ratio is 319.8 divided by 82.4, about 3.881. That $100 from 1980 equals roughly $388.11 in 2025 dollars, a total change of about 288 percent over 45 years, which annualizes to an average rate of roughly 3.1 percent a year.
| Input | Value |
|---|---|
| Amount | $100 (1980) |
| CPI 1980 / CPI 2025 | 82.4 / 319.8 |
| Equivalent in 2025 | ≈ $388.11 |
| Total inflation | ≈ +288.1% |
| Average annual rate | ≈ 3.1% |
The optional year-by-year breakdown
What it shows
When enabled and the span is 50 years or fewer, the tool renders a row for every year between your two selected years, showing that year’s CPI value, the year-over-year percentage change, and what your original amount was worth at that point in time.
Why the 50 year cap
It is purely a display choice to keep the table from becoming unreasonably long, the underlying two-point ratio calculation works correctly across the entire 1913 to 2025 range regardless of whether the year-by-year table is shown.
This tool provides historical purchasing power estimates for education and general reference. It is not a substitute for official BLS publications and not financial or investment advice, particularly for years close to the present where the annual average figure may still be subject to minor revision.
- U.S. Bureau of Labor Statistics, Consumer Price Index, the official source for the CPI-U figures this tool’s table is built from.
- BLS CPI Inflation Calculator, the government’s own equivalent tool, useful for cross-checking results.
- Federal Reserve Bank of Minneapolis inflation calculator, another CPI-based reference calculator with a longer historical view.
Questions about money over time
Adjusting a historical salary or price into today’s dollars for a fair comparison, checking whether a raise actually kept pace with inflation over a given period, converting an old contract value or court judgment amount into current terms, putting a grandparent’s story about decades old prices into context, and building inflation adjusted charts for a research or business report.
Questions About the Inflation Calculator
This calculator uses the US Bureau of Labor Statistics (BLS) Consumer Price Index for All Urban Consumers (CPI-U), Series CUUR0000SA0, with base period 1982 to 84=100. The CPI-U measures price changes across approximately 93% of the US population. Annual average values are used rather than monthly values, so the results represent full year averages rather than month to month snapshots. Data covers 1913 to 2025.
The formula is: adjusted amount = original amount multiplied by (CPI in target year divided by CPI in base year). For example, to find what $100 in 1980 is worth in 2025: CPI 1980 = 82.4, CPI 2025 = 319.8, ratio = 319.8 / 82.4 = 3.881. So $100 x 3.881 = $388.10 in 2025 dollars. This tells you that prices in 2025 are about 3.88 times higher than in 1980, $100 in 1980 had the same purchasing power as roughly $388 today.
CPI-U covers all urban consumers (about 93% of the US population) and is the most commonly cited inflation measure. CPI-W (Urban Wage Earners and Clerical Workers) covers a subset of the urban population, roughly 28%, focused on wage earners. CPI-W is used to calculate Social Security COLA adjustments. For general inflation research and historical dollar comparisons, CPI-U is the standard choice. There is also the Chained CPI (C-CPI-U), which accounts for consumer substitution and tends to show slightly lower inflation than CPI-U.
The 1970s inflationary period was driven by multiple converging factors. The 1973 OPEC oil embargo quadrupled oil prices, raising the cost of goods and transportation across the economy. Expansionary fiscal policy in the late 1960s (funding the Vietnam War and Great Society programs) had already increased money supply. The abandonment of the gold standard in 1971 removed a key constraint on dollar creation. Peak annual CPI-U inflation hit 13.5% in 1979. Federal Reserve Chair Paul Volcker broke the inflation cycle by raising interest rates sharply (the federal funds rate reached 20% in 1981), causing a painful recession but bringing inflation under 4% by 1983.
No. This calculator uses the national CPI-U, which is a weighted average across the entire United States. The BLS does publish regional CPI data and city specific indices, but these are only available for larger metropolitan areas and shorter time spans. Housing costs, for example, vary enormously by region, San Francisco and rural Mississippi have very different inflation experiences for housing. For most general comparisons, the national CPI-U is the appropriate benchmark.
The CPI is designed to measure average price changes for a representative consumer, so it may not match any individual experience. It can understate inflation for groups who spend heavily on housing in high cost areas, medical care (which tends to rise faster than overall CPI), or college tuition. It may overstate inflation because it does not fully account for quality improvements (a newer laptop costs the same but does far more), or for the shift to cheaper substitutes when prices rise. These limitations are well documented by economists and are why the BLS also publishes the Chained CPI and several other specialized indices.
Yes, this is a common use. If a role paid $50,000 in 2000, you can calculate what that is worth in today’s dollars to assess whether current compensation is genuinely competitive. The result tells you the real (inflation adjusted) value. Keep in mind that wage growth and inflation do not always track together, some sectors have seen real wage growth, meaning wages rose faster than inflation, while others have seen real wage decline. For salary benchmarking, compare the inflation adjusted figure to current market rates in your specific field and location.
Deflation is when the general price level falls, a dollar buys more over time rather than less. The US experienced mild deflation during 1921, 1927 to 1928, the Great Depression years 1930 to 1933, and briefly in 2009. The calculator handles this correctly: if CPI in the target year is lower than in the base year, the ratio is below 1 and the adjusted amount will be smaller than the original, reflecting that money was worth more (not less) in the target year. Total inflation will show as a negative percentage in those cases.
From the blog
Money, explained without jargon
Longer pieces on the maths behind loans, investing and pay.