
Finance calculators online, with the formula shown
Loan repayments, compound growth, break even points, take home pay, inflation and returns. Every calculator here shows the equation it used, so you can check the answer rather than trust it.
The finance toolkit
Calculators covering borrowing, saving, earning and pricing.
The four equations behind most of these tools
If you want to check a result by hand, or rebuild it in a spreadsheet, these are the formulas being applied.
P principal · r annual rate as a decimal · n compounds per year · t years · A final amount. Move from annual to monthly compounding at the same headline rate and the result rises, which is why the comparison rate matters more than the advertised one.
P loan amount · i monthly rate, the annual rate over 12 · n number of months. This is the same amortisation formula behind Excel PMT. Early payments are mostly interest, and the crossover to mostly principal comes later than most people expect.
The denominator is contribution margin, the amount each sale contributes to covering fixed costs. If it is zero or negative, no volume ever breaks even, which the tool flags rather than returning an absurd number.
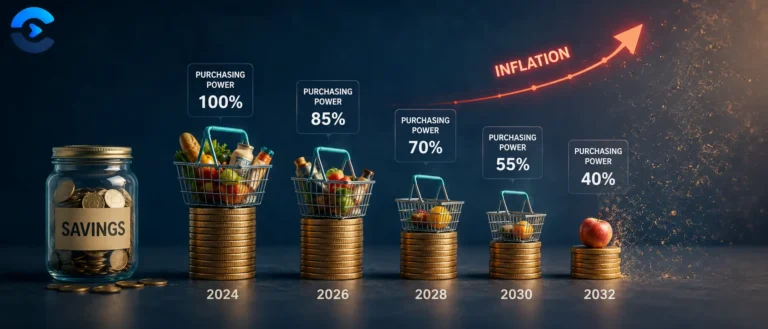
Subtracting inflation from your return is the common shortcut and it is wrong, mildly at low rates and badly at high ones. This is the Fisher equation, and it is what the inflation calculator uses.
Why the last decade does more work than the first three
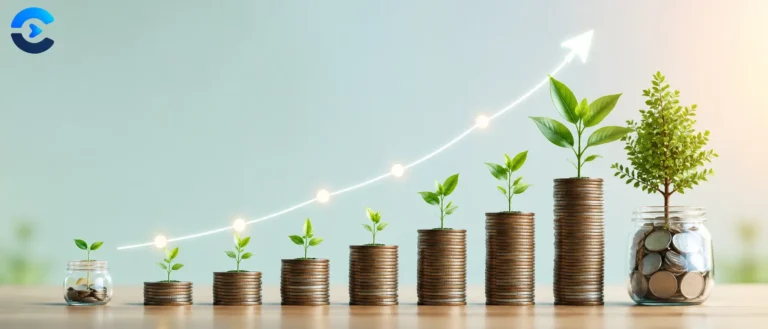
£10,000 at 7 percent, left alone. The growth is not a straight line, and the shape is the entire argument for starting early.
The first five years add £4,000. The last five add £11,100 from the same rate on the same untouched pot. Nothing changed except the base the percentage applies to. This is also why debt at 20 percent is so punishing in the other direction, and why the loan overpayment calculator shows interest saved rather than just a shorter term.
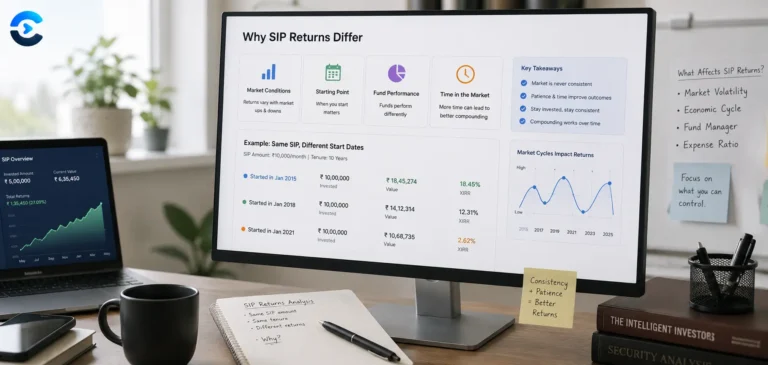
One caveat on every projection here: a constant annual rate is a modelling convenience. Real markets deliver lumpy returns, and two portfolios with identical average returns can end up far apart depending on the order those returns arrived in.
Where these calculators stop being useful
Knowing the boundary of a model is part of using it well.
| Tool | Assumes | Which breaks when |
|---|---|---|
| Compound interest | A fixed rate, reinvested, no fees or tax | Platform fees, dividend tax or a variable rate apply |
| Loan EMI | Fixed rate for the whole term, no fees | The rate is variable, or arrangement fees are rolled into the balance |
| Take home pay | Headline bands, standard allowance | You have salary sacrifice, benefits in kind, a student loan or regional variation |
| Currency | The mid market rate | You actually transact, where a spread and transfer fee apply |
| Retirement projection | Steady contributions and steady returns | Reality, which supplies neither |
For UK tax specifics, the current rates and allowances are published by HMRC. For US federal brackets, the IRS publishes them annually. Both change more often than most calculators are updated, this one included, so check the year.
More toolkits
Every category on ConvertNow, free and growing.
Money, explained without jargon
Longer pieces on the maths behind loans, investing and pay.
Questions about these finance calculators online
What these tools model, what they assume, and where the limits are.
Is any of this financial advice?
Which countries does the take home pay calculator cover?
Are the exchange rates live?
What compounding frequency do the interest tools use?
Why does my bank quote a different monthly repayment?
Do the investment tools account for tax and fees?
How much should I trust the retirement projection?
Is my salary or debt information stored?
What these numbers can and cannot tell you
These are calculators, not advice. The distinction matters more in this category than anywhere else on the site.