Loan Overpayment Savings Calculator: Extra $100 a Month
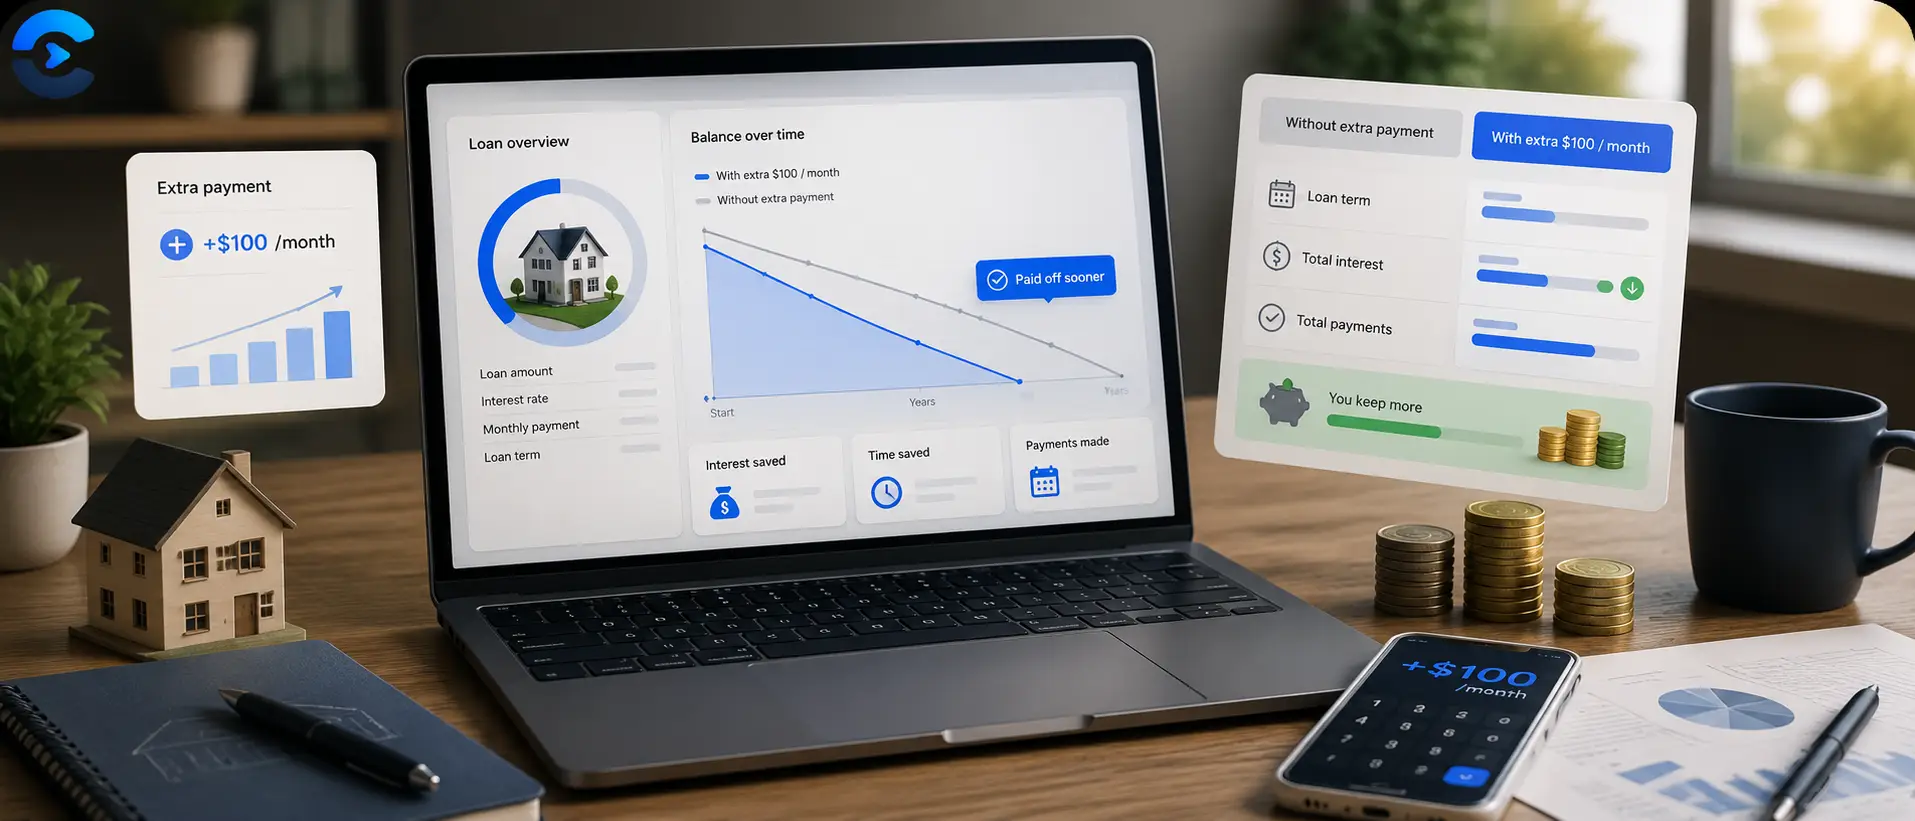
Take a $300,000 loan at 6.5 percent over 30 years. The standard payment runs about $1,896 a month, and paid on schedule it costs roughly $382,600 in total interest over the full term. Add just $100 a month on top of that payment, directed at principal, and the loan is paid off around 4 years early, in about 26 years instead of 30, while total interest drops to roughly $321,600, a savings of close to $61,000. That is the kind of shift a loan overpayment savings calculator shows in seconds, and the exact numbers change with your own balance, rate, and term, so a calculator built for your specific loan is the only way to see your real figures.
Take a $300,000 loan at 6.5 percent over 30 years. The standard payment runs about $1,896 a month, and paid on schedule it costs roughly $382,600 in total interest over the full term.
Why $100 a month moves the needle so much
Early in a loan, most of each payment goes toward interest, not principal. On the $300,000 example above, the very first payment of $1,896 sends about $1,625 to interest and only about $271 to principal. An extra $100 sent straight to principal on top of that does not just chip away at the balance today, it also removes that $100 from every future interest calculation for the rest of the loan. That compounding effect, working in your favor instead of against you, is why a fairly small monthly amount produces a large total savings figure.
This is also why the timing of an overpayment matters. A dollar of extra principal paid in year 1 saves more total interest than a dollar paid in year 25, because it has more remaining months to keep compounding down the balance. If you want to see how compounding works in the other direction, building up rather than paying down, the compound interest calculator shows the same math applied to savings and investments.
The before and after, side by side
Here is the same $300,000 loan at 6.5 percent for 30 years, run two ways.
Standard schedule, no extra payments: monthly payment of about $1,896, full 30 year term, total interest paid of roughly $382,600.
With an extra $100 a month toward principal from the first payment onward: same $1,896 base payment plus $100, loan paid off in about 312 months, which is 26 years, and total interest paid of roughly $321,600.
The difference is about 48 months shaved off the payoff date, close to 4 years, and about $61,000 less paid in interest over the life of the loan. None of that changes the loan's principal or interest rate. It only changes how fast the balance shrinks.
Run your own overpayment numbers
The $300,000 example above is one scenario out of thousands. Your balance, rate, and remaining term will produce a different payoff date and a different interest savings figure. Our free Loan Overpayment Impact Visualizer takes your actual loan details and shows the new payoff timeline and total interest saved side by side with your current schedule, instantly.
Open the Loan Overpayment Impact VisualizerWhy a calculator beats doing this by hand
The math behind these numbers is an amortization schedule, recalculated month by month as the balance drops faster than scheduled. Working that out by hand for 300 or more months is not practical, and small rounding errors compound just like the interest does. A loan overpayment savings calculator runs the full schedule instantly for your actual balance, rate, and term, and shows both the new payoff date and the new total interest figure without the manual work.
The same logic applies whether the loan is a mortgage, an auto loan, or a personal loan. If you first want to see what your current required payment looks like before adding anything extra, the loan EMI calculator breaks down the standard monthly payment on any loan amount, rate, and term.
Where the extra $100 has to come from
An overpayment only works if it is money you can consistently spare each month without straining other bills. Before committing to an extra $100, it helps to look at what actually lands in your account after taxes and deductions. The take home pay calculator gives a clear picture of your real monthly income, which makes it easier to judge whether $100 a month is comfortable or whether a smaller extra payment, say $50, still produces a meaningful reduction in your payoff timeline.
The Consumer Financial Protection Bureau publishes general information on how extra principal payments affect a mortgage, including reminders to confirm with your loan servicer that extra payments are applied to principal and not simply held toward next month's bill. That confirmation step matters, because a payment misapplied as an early next payment instead of a principal reduction will not produce the interest savings shown here.
What changes if your loan terms are different
The $61,000 figure above is specific to a $300,000 balance at 6.5 percent over 30 years. A smaller loan, a shorter term, or a lower rate will produce a smaller dollar savings from the same $100 overpayment, simply because there is less interest accruing in total. A larger balance or a longer remaining term tends to produce a bigger savings figure from the same extra amount, since more months remain for the compounding effect to work. This is exactly why the number needs to be run against your own loan rather than borrowed from someone else's example.
Other loan and savings calculators
Overpayment planning usually starts with understanding your current loan and budget. The loan EMI calculator shows your required monthly payment for any loan amount, rate, and term, which is the baseline you would be adding an overpayment on top of. The compound interest calculator is useful for comparing whether extra cash is better spent paying down debt or invested elsewhere. And the take home pay calculator helps confirm how much room your monthly budget actually has before committing to a fixed extra payment. You can browse the full set of finance tools, or check the ConvertNow blog for more explainers like this one.
Is $100 extra worth it?
An extra $100 a month on a $300,000 loan at 6.5 percent over 30 years cuts the payoff time by about 4 years and saves roughly $61,000 in total interest. The exact figures for your own loan will differ based on your balance, rate, and remaining term, so treat this as a factual illustration rather than a personalized recommendation. Run your own numbers through the Loan Overpayment Impact Visualizer to see your real payoff date and real interest savings before deciding how much extra to send each month.
Loan Overpayment Savings Calculator: Four More Ways to Test Your Plan
The $100 example is one setting on one dial. A loan overpayment savings calculator lets you turn every dial, and the results are often surprising. Here are four extra tests on the same $300,000 loan at 6.5 percent over 30 years, each one run through a loan overpayment savings calculator month by month.
What does a loan overpayment savings calculator show at $50, $200 and $500?
The savings do not scale in a straight line. Doubling the extra payment saves more than double the interest, because every dollar also shortens the number of months in which interest accrues. Here is how a loan overpayment savings calculator reads each level.
| Input in the loan overpayment savings calculator | Payoff time | Total interest | Interest saved |
|---|---|---|---|
| $0 extra, loan overpayment savings calculator run | 360 months | $382,633 | None |
| $50 extra, loan overpayment savings calculator run | 334 months | $349,052 | $33,582 |
| $100 extra, loan overpayment savings calculator run | 312 months | $321,639 | $60,995 |
| $200 extra, loan overpayment savings calculator run | 277 months | $279,185 | $103,449 |
| $500 extra, loan overpayment savings calculator run | 210 months | $202,874 | $179,759 |
Every row came from the same loan overpayment savings calculator logic. Notice the jump from $50 to $100. Twice the effort buys about $27,400 more savings. Seeing that pattern is the main reason to use a loan overpayment savings calculator before you pick a number.
How does a loan overpayment savings calculator treat a one time lump sum?
Maybe you get a bonus or a tax refund and would rather pay it once. Enter the amount as a single payment and the loan overpayment savings calculator drops the balance on day one. A lump sum works hard because it hits the loan while the balance is largest.
| Lump sum test | Payoff time | Interest saved |
|---|---|---|
| $5,000 once, loan overpayment savings calculator scenario | 343 months | $28,411 |
| $10,000 once, loan overpayment savings calculator scenario | 327 months | $53,917 |
Compare that with the monthly route. Paying $100 for 12 months is only $1,200 out of pocket, so the strength of a monthly habit lies in its length, not in the first year. Test both inputs in your loan overpayment savings calculator side by side.
Is a late start still worth modeling in a loan overpayment savings calculator?
Yes, but expect a smaller reward from the loan overpayment savings calculator. We ran the same $100 a month starting at three different points in the loan.
- Start in month 1: payoff at 312 months, interest saved about $60,995 in the loan overpayment savings calculator.
- Start after 10 years: payoff at 337 months, interest saved about $22,166.
- Start after 20 years: payoff at 352 months, interest saved about $4,510.
So waiting 10 years costs roughly $38,800 of potential savings from the very same $100. One loan overpayment savings calculator run makes that trade obvious, which helps when you must choose between starting small today or waiting for a bigger raise.
Check before you pay
Look for prepayment penalties in your contract. Some auto and personal loans charge a fee for early payoff, and a loan overpayment savings calculator will not include it unless you enter it.
What should you check after using a loan overpayment savings calculator?
A loan overpayment savings calculator gives you a target. Your bank decides what actually happens. Run through this short list before you set up the extra payment.
- Confirm in writing that extra money goes to principal.
- Ask whether the loan carries an early payoff fee.
- Keep an emergency fund of at least 3 months of expenses first.
- Rerun the loan overpayment savings calculator each year, since your balance and income will have moved.
- Save a printout from the loan overpayment savings calculator so you can compare it with your real statements.
The figures above are illustrations for one loan, not advice. Your own balance and rate will change every row, so enter real numbers in the loan overpayment savings calculator before you decide. Used well, a loan overpayment savings calculator turns a vague hope into a plan with a date on it.
| In this guide |
|---|
| Why $100 a month moves the needle so much |
| Why a calculator beats doing this by hand |
| What changes if your loan terms are different |
| Is $100 extra worth it? |
FAQ: Loan Overpayment Savings Calculator: Extra $100 a Month
What does a loan overpayment savings calculator actually show?
It shows how much time and interest you save by paying more than the required monthly amount on a loan, comparing your standard payoff schedule against a schedule with extra principal payments added in.
Does an extra $100 a month really save tens of thousands in interest?
On a $300,000 loan at 6.5 percent over 30 years, yes, the savings come out to roughly $61,000 in this example. Smaller loans or shorter terms will show a smaller dollar figure, since there is less total interest to remove.
How many years earlier will my loan be paid off with a $100 overpayment?
In the $300,000 example, the payoff moves up by about 4 years, from 30 years to about 26 years. The exact number of years saved depends on your own balance, rate, and remaining term.
Do I need to tell my lender the extra payment is for principal?
Yes, in most cases. Some lenders apply extra payments toward next month's bill by default instead of reducing principal, so it is worth confirming with your servicer that the extra amount is marked for principal reduction.
Does it matter when in the loan term I start overpaying?
Yes. Extra principal paid earlier in the loan has more remaining months to reduce future interest charges, so starting an overpayment plan sooner produces a larger total interest savings than starting the same amount later.
Is paying extra on a loan always the better use of spare money?
Not necessarily. It depends on your loan's interest rate compared to what that money could otherwise earn or what other debts might cost. This article explains the mechanics of overpayment, not personalized financial advice for your situation.
Can I use this same math for an auto loan or personal loan, not just a mortgage?
Yes. The amortization math behind a loan overpayment savings calculator applies to any fixed rate installment loan, including auto loans and personal loans, not only mortgages.
What information do I need before running my own numbers?
You need your current loan balance, your interest rate, your remaining term in months or years, and the extra amount you plan to pay each month. With those four figures, a calculator can show your exact new payoff date and interest savings.
Sources and further reading
- Amortization calculator on Wikipedia: the payment formula used in this example.
- Consumer Financial Protection Bureau: guidance on prepaying mortgages and loans.