SIP Calculator: Calculate Your Mutual Fund SIP Returns
Estimate how much your monthly SIP investments could grow over time. Model step-up SIPs, lump sum top-ups, and inflation-adjusted returns instantly, no sign up needed.
SIP Calculator
Project what a monthly systematic investment grows into, with optional annual step-up and inflation adjustment.
Returns are compounded monthly and assume the investment is made at the start of each month. Markets do not deliver a constant return, so treat this as a planning estimate rather than a forecast. Exit load, expense ratio and capital gains tax are not deducted.
Why this SIP calculator simulates month by month instead of using one closed-form formula
A systematic investment plan, a fixed amount invested every month into the same fund, has a well known closed form future value formula when the amount never changes. This tool doesn’t use that shortcut. It simulates the investment one month at a time, which is the only way to correctly handle a step up SIP, where your monthly contribution itself grows every year, something the plain formula can’t express.
The month by month engine
Worked example: $5,000 invested every month for 10 years, no step up, at an expected 12% annual return, meaning a 1% monthly rate. Simulated month by month, the maturity value comes out to roughly $1,161,700. Total invested over those 120 months is a flat $600,000, so the wealth gained is about $561,700, a return on invested capital near 93.6%. That figure is close to the textbook annuity due formula P × [((1+i)^n − 1) / i] × (1+i), which the loop reproduces exactly when there’s no step up.
| Input | Value |
|---|---|
| Monthly investment | $5,000 |
| Expected annual return | 12% (1% monthly) |
| Duration | 10 years (120 months) |
| Total invested | $600,000 |
| Maturity value | ≈ $1,161,700 |
| Wealth gained | ≈ $561,700 (93.6%) |
Step-up SIP: why it needs simulation, not algebra
Turn on the step up option and enter, say, a 10% annual increase, and every twelfth month your contribution jumps by that percentage compounded on itself. Year one invests the base amount, year two invests it times 1.1, year three times 1.21, and so on. There’s no single clean formula for the future value of a growing annuity with monthly compounding layered under annual step increases, so the loop is the calculation, not just a display convenience.
Lump sum add-on
An optional lump sum is added as the starting corpus before month one begins, then compounds alongside every subsequent monthly contribution for the full duration.
Year by year table
Every twelve months, the running invested total and corpus value are snapshotted into a row, so you can see exactly when the growth curve starts to outpace your own contributions.
CSV export
The full yearly breakdown, invested amount, value, and gain per year, downloads as a CSV file for anyone who wants to model this in their own spreadsheet.
Real market returns aren’t a smooth constant monthly rate, they’re volatile year to year. This tool projects a straight line average return for illustration, which will always look smoother than an actual fund’s performance history.
Systematic investing references
- Annuity, Wikipedia covers the annuity-due versus ordinary annuity distinction this calculator’s compounding order relies on.
- SEBI investor brochure on systematic investment plans explains the SIP mechanism this tool models numerically.
Goals people plan with SIPs
Projecting a retirement corpus from a fixed monthly contribution, comparing how much faster a step up SIP builds wealth versus a flat monthly amount, testing whether a given monthly investment realistically reaches a target purchasing power after inflation, and deciding how a one time bonus deposited as a lump sum changes the final maturity value.
Frequently Asked Questions
A Systematic Investment Plan (SIP) lets you invest a fixed amount into a mutual fund at regular intervals, usually monthly, instead of investing a lump sum at once. Each installment buys units at that day’s Net Asset Value (NAV), which averages your purchase cost over time (rupee cost averaging) and removes the need to time the market. Over long periods, SIPs benefit from compounding as returns generated in earlier months themselves start earning returns.
The standard formula is FV = P × [((1+i)^n − 1) / i] × (1+i), where P is the monthly investment, i is the monthly rate of return, and n is the total number of months invested. The (1+i) at the end accounts for the fact that SIP installments are typically deducted at the start of the month (annuity due), so each installment gets one extra month of compounding compared to a standard end-of-month annuity.
A step-up (or top-up) SIP automatically increases your monthly investment amount by a fixed percentage every year, usually matching your expected salary growth. Since most people’s income rises over their career, a step-up SIP lets your investments grow proportionally, which can significantly increase your final corpus compared to a flat SIP of the same starting amount. It’s worth using if you expect steady income growth and want to accelerate wealth creation without feeling a bigger pinch early on.
Historically, diversified equity mutual funds and broad market indices have delivered annualized returns in the range of 10 to 14% over long periods (10+ years), though this varies significantly by market, fund category, and time frame, and past performance never guarantees future results. Debt funds typically return 6 to 8%, while hybrid funds fall in between. It’s prudent to use a conservative assumption (10 to 12%) for long-term planning rather than extrapolating a recent bull market.
Neither is universally better, it depends on market conditions and your cash flow. SIP works well when you don’t have a large sum to invest at once, or when markets are volatile, since it averages your purchase price across highs and lows. Lump sum investing tends to outperform SIP in strongly rising markets, since more money is invested from day one and compounds for longer. For most individual investors investing from regular income, SIP is the more practical and disciplined approach.
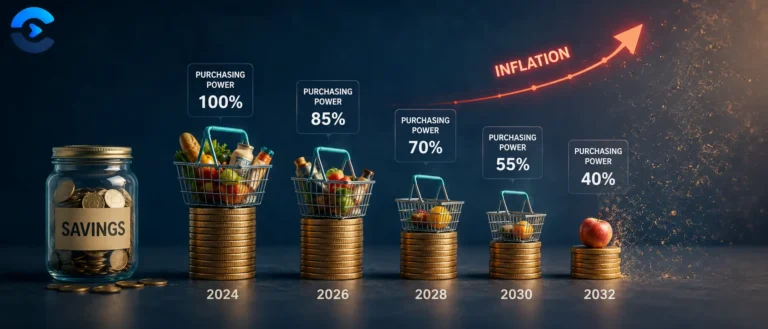
Inflation erodes the purchasing power of money over time, so a maturity value of $500,000 in 20 years will not buy as much as $500,000 today. This calculator’s inflation adjustment divides your projected maturity value by (1 + inflation rate) raised to the number of years invested, giving you the equivalent value in today’s money. Comparing your nominal returns to inflation (real returns) is essential when planning for long-term goals like retirement.
Yes, most mutual funds allow you to pause a SIP for a limited period (commonly up to 3 months) or cancel it entirely without penalty, since a SIP is simply a standing instruction to your bank, not a binding contract. However, stopping a SIP partway through a long-term goal breaks the compounding momentum and rupee cost averaging benefit, so it’s generally better to reduce the amount rather than stop entirely if you’re facing a temporary cash crunch.
No, this calculator projects gross returns based on your assumed annual rate and does not deduct fund expense ratios, exit loads, or capital gains tax, all of which reduce your actual take-home returns. Expense ratios for equity funds typically range from 0.5% to 2% annually, and long-term capital gains above a threshold are taxed in most jurisdictions. For a more precise net figure, subtract your fund’s expense ratio from the expected return before calculating, and account for applicable taxes on withdrawal.
From the blog
Money, explained without jargon
Longer pieces on the maths behind loans, investing and pay.